Inside This Article:
- Construction defect lawsuits are creating growing financial pressure for some of the nation’s largest homebuilders, according to a recent Wall Street Journal report.
- Labor shortages, rising costs, and accelerated construction schedules may contribute to defect-related risks.
- Construction defect lawsuits often name contractors, architects, engineers, and other professionals, all of whom typically need to carry Commercial General Liability (CGL) Insurance and Professional Liability Insurance.
- Builder documentation, subcontractor oversight, and long-term coverage planning can help construction firms manage construction defect risks.
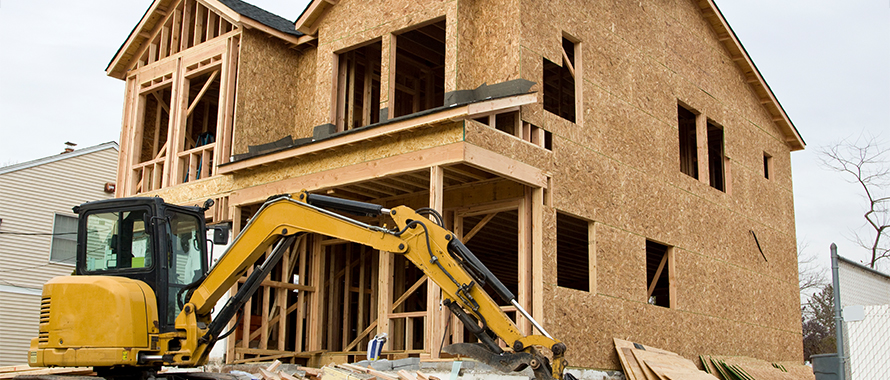
Long after the last nail is driven, construction defects can come back to haunt builders — in fact, several of the nation’s largest homebuilders are facing a surge of construction defect allegations, according to a recent Wall Street Journal report. Homeowners across multiple states have filed lawsuits against builders such as D.R. Horton, Lennar, and PulteGroup, alleging problems ranging from foundation movement and water intrusion to mold and other defects that were reportedly discovered after the homes were completed.
Homeowners have argued that today’s builders are cutting corners and producing “shoddier, error-ridden homes,” the publication reported, while builders say the claims account for a small fraction of their homes — and believe plaintiffs’ attorneys may be recruiting homeowners into questionable lawsuits.
Construction defect claims are “100% trending right now,” said Ryan Wallace, Broker, Professional Liability, Burns & Wilcox, Indianapolis, Indiana. “We are in a very litigious environment.”
[Construction defect claims are] 100% trending right now. We are in a very litigious environment.
As lawsuits grow, some major builders have substantially increased the funds they set aside for current and future claims, the newspaper reported. Depending on the allegations, claims may involve both construction-related issues and professional services, making it important for contractors, architects, engineers, and other professionals to carry Construction Insurance policies such as Commercial General Liability (CGL) Insurance, Professional Liability Insurance, and Excess Liability Insurance.
Construction defect claims often involve both Professional Liability and General Liability exposures. Without adequate insurance protection, a significant claim can have serious financial consequences for a construction firm and, in some cases, threaten its ability to continue operating.
Labor shortages, demand may fuel defect claims
Several factors may be contributing to the increase in construction defect claims activity, Wallace said, including labor shortages, supply chain disruptions, and increased demand for new housing. The construction industry was expected to need an estimated 349,000 net new workers in 2026 to meet anticipated demand, according to Associated Builders and Contractors.
Labor shortages, rising costs, and pressure to complete projects quickly can create conditions that increase the risk of construction defects. “The labor shortages are leading to inexperienced workers, and when you get inexperienced workers, they might not know what they need to be doing,” he said. “That can affect the building process.”
Cutting corners is another concern, whether due to supply shortages and substitutions or rushing, Wallace added. “Development is just huge right now. There is increased pressure to build these homes quickly to meet the demand of the homebuyers,” he said. “Homeowner awareness and their willingness to pursue litigation” is another factor, he said.
While some industry professionals have not observed a dramatic increase in construction defect claims frequency, elevated levels of residential construction activity may be contributing to greater claim volume overall. Common allegations include structural defects, water intrusion, electrical issues, improperly designed landscaping that leads to flooding, and plumbing errors.
Many construction defect claims involve latent defects that are not immediately apparent when a project is completed. Instead, these issues may emerge years later, after conditions have deteriorated or the defect has had time to develop.
How insurance policies can respond to construction defects
According to the Wall Street Journal report, recent construction defect cases include allegations from the Seminole Tribe of Florida that homebuilder Lennar built more than 450 homes with roof problems, and claims from thousands of homeowners in Louisiana that their homes by D.R. Horton failed to keep out moisture. In Las Vegas, about 50 homeowners in a retirement community have been in a dispute with PulteGroup over alleged sinking foundations and other construction issues, FOX5 recently reported.
Construction defect lawsuits often expand beyond a single construction firm and may name the general contractors, developers, architects, engineers, design-build firms, and specialty subcontractors involved in the work.
“An artisan contractor, roofing contractor, or even the construction managers overseeing the project could be named in the lawsuit,” Wallace said. “Even firms with a limited role often get pulled into litigation simply because they were involved in the project.”
Allegations involving bodily injury or property damage may trigger CGL Insurance, while claims stemming from professional services may require Professional Liability Insurance, also known as Architects & Engineers Professional Liability Insurance. These policies can help respond to covered legal expenses, settlements, judgments, repair costs, and more.
“Many of the construction defect allegations we are seeing stem from professional services,” Wallace said. “CGL Insurance policies may not respond to claims that arise from design decisions, plans or specifications, or professional advice. The Professional Liability Insurance is going to fill that gap for the financial damages caused by errors or omissions or negligence in professional services.”
Many of the construction defect allegations we are seeing stem from professional services.
Contractors can also face Professional Liability exposures when they identify potential issues with plans, specifications, or construction methods but fail to address them. A failure to raise concerns or take corrective action may increase the likelihood of a claim.
Carrying both CGL Insurance and Professional Liability Insurance can help construction firms address a broader range of potential claims. Because construction defect allegations may involve a combination of bodily injury, property damage, and professional services exposures, maintaining both coverages can help close potential gaps in protection.
Preparing for the risk of long-term claims
Because construction defect claims can surface years after work is complete, maintaining continuous coverage is important. Wallace noted that Professional Liability Insurance is typically written on a claims-made basis, making Extended Reporting Periods (ERP), also known as Tail Coverage, worth considering when a business is sold or ceases operations. “Contractors will want to have continuous coverage in order to make sure they are properly covered years down the road,” he said.
Builders should maintain detailed project documentation and retain records for an extended period, given that construction defect claims may emerge years after project completion. Construction firms should also carefully vet subcontractors, verify that they carry adequate insurance, and ensure contracts include appropriate hold-harmless and indemnification provisions.
Depending on their operations and risk profile, construction firms may also benefit from additional coverages such as Excess Liability Insurance or Contractors Pollution Liability Insurance. Excess Liability Insurance can provide an additional layer of protection above primary policy limits when severe claims occur.
Due to the overlap of responsibilities on design-build projects, Wallace said, finger-pointing is common when allegations arise. Even when a firm feels they are not responsible for a defect, “the defense costs can add up quickly,” he said. “Everything today is more and more expensive.”