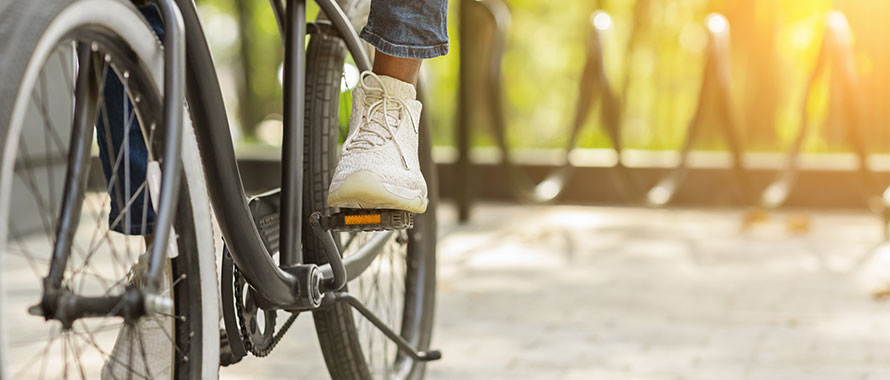
A woman who fell off her bike and was injured while leaving her workplace at the University of California will be eligible for Workers Compensation but cannot sue her employer for negligence, an appeals court ruled. Based on the “premises line” rule, the employee was still engaged in the course of her employment when the accident occurred, as she was still on the employer’s property, the Society for Human Resource Management reported on Nov. 9.
Featured Solutions
Employees who are eligible for Workers Compensation benefits generally cannot sue their employer for the same injury. This exclusivity provision helps protect businesses from significant financial losses stemming from workplace injury claims.
It is not white and black — there is always going to be that gray area. You never know what is going to happen in a court of law.
Each state has its own laws on Workers Compensation Insurance claims, though some “gray areas” remain, said Morgan McCoy, Underwriter, Workers’ Compensation, Burns & Wilcox, Charleston, South Carolina.
“It is not white and black — there is always going to be that gray area,” McCoy said. “You never know what is going to happen in a court of law. It is really on a state-by-state, case-by-case basis.”
Determining when an employee is ‘at work’
Although an employee would not usually be covered by Workers Compensation Insurance while traveling to or from work, courts in California have established that an employee’s work technically begins when they enter the employer’s premises and ends when they have left the premises, SHRM reported. State guidelines vary, and in New Jersey courts are currently weighing an appeal over whether a worker injured on his commute should be eligible for Workers Compensation, Law.com reported in September.
Questions about whether an injury occurred in the course of employment arise frequently.
Being injured after work hours while still on a company’s property is not unheard of; for example, Insurance Business reported in March that Workers Compensation claims from e-scooter incidents have tripled over the past three years, with 36% of these crashes occurring on the way to work and 29% on the way home.
The question of whether or not an injured worker was hurt in the course of their employment comes up often, McCoy agreed. For example, he referenced a claim in California in which a retail store worker was found to be eligible for Workers Compensation after being injured in a mall common area.
“Because she was forced to walk through the mall to get to her job, and there was not a back entrance, they had to pay the claim out,” McCoy said. “It was not in the employer’s hands as much as something would be if it was on their property. Every case is a little bit different.”
Uncertainty surrounding workplace injuries has also arisen over the increase in remote work. As of March, a Pew Research Center poll found that about a third of workers whose jobs could be done remotely were working from home, compared to just 7% prior to the pandemic.
The growth of remote work has created additional challenges when determining whether an employee was actively working at the time of an injury. Household tasks such as lawn mowing or laundry may take place during the workday, and some states continue to refine how these situations are addressed.
To address this potential gray area, some employers have suggested video monitoring of employees’ workstations, McCoy said. “Remote work is one of those things that insurance carriers overall are trying to figure their way through,” he said. “It is in its infancy as far as what employers are doing.”
‘Each state is going to be different’
Employers should familiarize themselves with their state’s Workers Compensation regulations, as some states provide broader interpretations than others regarding what constitutes being in the course of employment. Care should also be taken when requiring employees to run errands or participate in work-related activities outside of the workplace. In some states, injuries that occur while performing a task at the employer’s direction may be covered by Workers Compensation.
“Each state is going to be different,” McCoy added. “They all have different laws.”
Despite being regulated by individual states, Workers Compensation Insurance is generally “very straightforward,” McCoy said. It provides payments for an injured worker’s medical treatment, a portion of lost wages, rehabilitation and other expenses.
Workers Compensation Insurance generally covers medical treatment for employees who suffer covered workplace injuries, regardless of industry. Coverage can include treatment received at a hospital, urgent care facility or other approved medical provider.
This policy is always triggered first when a worker is injured, although further liability claims are possible in some cases and could be covered by the employer liability portion of a Workers Compensation Insurance policy, or a company’s Commercial General Liability (CGL) Insurance and other policies.
Employees are generally prohibited from suing their employer over workplace injuries covered by Workers Compensation. Exceptions are uncommon and typically involve allegations that an employer knowingly or intentionally created unsafe working conditions.
This distinction underscores the important role Workers Compensation Insurance plays by providing benefits to injured employees while helping protect businesses from additional financial exposure.
Business owners should understand the Workers Compensation laws in their state and take a cautious approach to workplace safety and employer-directed activities. Maintaining safe parking lots and walkways, particularly during winter weather, can help reduce the likelihood of injury claims. Employers should also clearly communicate whether attendance at after-hours events is mandatory or voluntary, as required participation could affect whether an injury is considered work-related.
Premiums continue to decline for Workers Compensation Insurance
Being safe at work is more important than ever for U.S. workers, according to an employee safety study released earlier this year, and 90% of workers said their company has a legal and moral duty to protect employees from unnecessary risk of harm on the job, EHS Today reported in March. Only about 54% of employees felt their safety was extremely important to their employer, and just 56% of workers had participated in a safety training more than once per year.
Avoiding workplace injuries starts with having safety guidelines and procedures in place. “One thing insurance carriers like employers to have is a safety manual with written employee guidelines,” McCoy said. “A lot of those will have entry and exit protocols and what the employees are supposed to do in an emergency.”
Employers can also take advantage of risk management services available through their Workers Compensation Insurance carrier, including loss control inspections. “The majority of carriers now have a lot of hands-on tools employers can use as far as loss control. They can help the employer become as safety-conscious as possible,” McCoy said. “Carriers have figured out that this helps bring down their losses.”
Employers should submit potential injury claims as quickly as possible.
Even when there is uncertainty about whether an injury will ultimately be covered, reporting the incident promptly can help ensure that coverage questions are addressed efficiently. Early reporting also allows carriers to investigate the circumstances and determine whether a claim exists.
The current Workers Compensation Insurance market makes it an attractive time for companies to review their coverage options. Premium rates have declined for years in many states, creating opportunities for employers to secure competitive pricing.
Even if it is a smaller company and it is not required, I would strongly recommend having Workers Compensation Insurance. Without it, you could end up having to pay out a claim and it could put you out of business.
According to McCoy, the continually declining rates “has never happened before.”
“It is definitely a great time to buy as far as premiums go,” he said. “If an employer has hired the amount of employees to where the state requires them to have the coverage, they need to make sure they purchase it. Even if it is a smaller company and it is not required, I would strongly recommend having Workers Compensation Insurance. Without it, you could end up having to pay out a claim and it could put you out of business. I would not leave myself open to something like that.”