Intel

Featured
Med Spa Hit With $25,000 Penalty Over Unauthorized Drugs
Inside This Article: An Ohio med spa was fined $25,000 after investigators found unauthorized prescription drug orders and other violations. A patient lost consciousness after using a drug provided by one of the med spa’s owners, according to the state investigation. Medical Malpractice Insurance and Commercial General Liability (CGL) Insurance can address different aspects of med spa risks. As
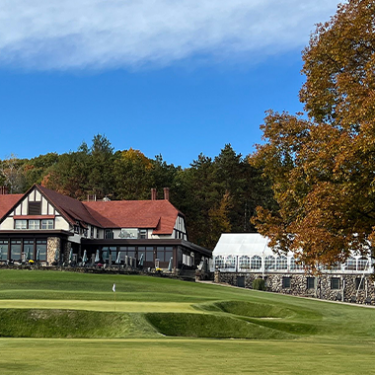
Century-Old Clubhouse Destroyed by Fire Faces Complex Rebuild
Inside This Article: A fire recently destroyed the historic Lochmoor Country Club clubhouse in Grosse Pointe Woods, Michigan. Historic properties may require specialized Commercial Property Insurance with Historical Replacement Cost to reproduce original materials, designs, and craftsmanship after a loss. Business Interruption Coverage and Extra Expense Coverage can help companies recoup lost revenue and maintain payroll during restoration. Updates
In the News
Trending
Other Recent Intel
Scenario 1: A subcontractor goes bankrupt mid-project, leaving a contractor with incomplete work and missing materials. RELATED STAT: According to a 2024 survey by the Associated General Contractors of America, 70% of contractors reported an increase in subcontractor defaults, with half experiencing project delays or cancellations as a result. SOLUTION: Professional Liability Insurance, such as Errors & Omissions (E&O) coverage,…
Key Takeaways: Seemingly minor changes in policy language can significantly alter how coverage responds for Construction risks, particularly when embedded within broader endorsements. Common exclusions and limitations—including Action Over, subsidence, and hot work provisions—can create gaps that may not be immediately apparent during placement. Aligning policy language with contractor operations and contractual obligations is essential to helping reduce unexpected coverage gaps and claim disputes. [button link=\"https://issuu.com/docs/f0637d3760be370e8b4a3620bbbbd7a0?fr=sN2E2MjkyMjc3ODc\"…
Scenario 1: A coastal community is hit by a hurricane, leaving many homes and businesses with extensive wind damage and flooding. RELATED STATS: Hurricane impacts can range from minor wind damage on a roof to a total loss, especially in cases of catastrophic flooding. U.S. homeowners collectively spend approximately $20 billion per year repairing their homes after storms. SOLUTION: Homeowners…
Scenario 1: A homeowner sought Flood Insurance for a property in New York with multiple structures, including barns and guest houses. RELATED STAT: The National Flood Insurance Program (NFIP) could not adequately cover the property due to its value and the number of buildings. SOLUTION: Burns & Wilcox was able to offer a comprehensive Flood Insurance program in the private…
Inside This Article: Construction defect lawsuits are creating growing financial pressure for some of the nation\'s largest homebuilders, according to a recent Wall Street Journal report. Labor shortages, rising costs, and accelerated construction schedules may contribute to defect-related risks. Construction defect lawsuits often name contractors, architects, engineers, and other professionals, all of whom typically need to carry Commercial General Liability…
Inside This Article: Weather-related losses continue to drive summer Homeowners Insurance claims as severe storms become more frequent and costly. Many homeowners remain vulnerable to flood losses because standard Homeowners Insurance policies typically exclude flooding. Liability exposures from pools, trampolines, and other summer activities can create significant financial risks for homeowners. Regular policy reviews can help homeowners identify coverage gaps and ensure protection keeps pace…
Powered by