Inside This Article:
- Falling debris from a vacant building at the historic Acme Saloon site in El Paso, Texas, recently sent one pedestrian to a hospital, according to reports.
- El Paso officials closed the sidewalk and said the building was “an imminent danger to public safety.”
- When a property owner is sued over an on-premises injury, Commercial General Liability (CGL) Insurance and Excess Liability Insurance can help cover medical expenses, legal defense, and more.
- Commercial Property Insurance and Ordinance and Law Coverage can cover physical damage and required code upgrades, while regular inspections and maintenance can help property owners reduce the risk of a loss.
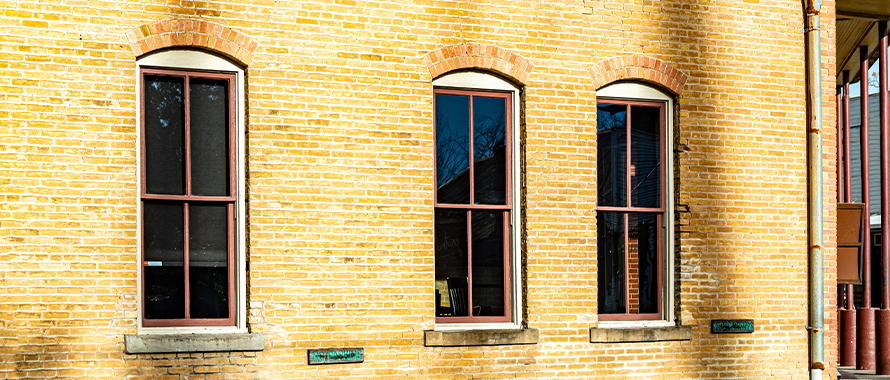
Falling debris from a vacant building at the historic Acme Saloon site in downtown El Paso, Texas, injured a pedestrian, prompting police to close the sidewalk and city officials to warn of an “imminent danger to public safety.” The pedestrian was taken to a hospital with minor injuries after pieces of the building’s cornice broke loose on Oct. 8, the El Paso Times reported.
Inspectors reportedly attributed the falling cornice to deterioration in its structural connections.
The accident “could have been a lot worse,” said Michelle Anaya, Underwriter, Commercial Insurance, Burns & Wilcox, San Antonio, Texas. “Here in El Paso, we have a lot of historic buildings,” she said. “Unfortunately, many of these buildings have not received the maintenance or upkeeping which they need, and it leads to these types of incidents.”
Unfortunately, many of these buildings have not received the maintenance or upkeeping which they need, and it leads to these types of incidents.
A claim or lawsuit following an injury can leave a building owner facing medical expenses, legal defense costs, and potential damages. “Without insurance, those expenses can be devastating,” Anaya said. Commercial General Liability (CGL) Insurance can help address third-party bodily injury claims, including incidents involving a building’s exterior.
“It is always important to have liability coverage, especially in this day and age where medical treatment and lawyer fees can get so expensive,” said Isaac Villalvazo, Underwriter, Commercial Insurance, Burns & Wilcox, The Woodlands, Texas. “Buying a liability policy upfront easily mitigates that expense.”
It is always important to have liability coverage, especially in this day and age where medical treatment and lawyer fees can get so expensive.
Vacant buildings still carry liability risks
According to the El Paso Times, the building is located at the historic site of the former Acme Saloon where outlaw John Wesley Hardin was killed in 1895. The building reportedly had no active work permits, and officials planned to notify the owner about addressing its condition. The incident underscores how a vacant building can still pose a risk to passersby, Villalvazo said.
“There is very little foot traffic going on inside the premises on a vacant building, but in this case, it was something exterior and it just happened to be on a sidewalk,” he said. “The liability exposure is definitely something that will always exist even in this scenario.”
Just days after the El Paso incident, on Oct. 16, wind tore roofing material loose at Frank Lloyd Wright’s Taliesin West in Scottsdale, Arizona, fatally injuring a man participating in a walking tour, Arizona’s Family reported.
Fatalities are an extreme example but possible “if it is something that is heavy enough or falls from high enough,” Villalvazo said. Even nonfatal injuries can generate substantial claims. According to Verisk’s May 2025 Executive Insights report, general liability claim severity increased 45%, from $70,000 in 2020 to $101,000 in 2024, with bodily injury as the main driver of overall losses.
A property owner without CGL Insurance to help pay for legal defense, settlements, and more would need the financial resources to address a claim, Anaya said. “The owner could need to sell the building to pay off the damages to that individual,” she said.
Matching insurance coverage to the risk
In addition to CGL Insurance, which can also cover medical expenses, lost wages, and other damages arising from third-party bodily injury claims, Excess Liability Insurance is typically recommended to property owners. Severe incidents are unpredictable, Villalvazo said, and additional liability limits above underlying policies can be critical.
“We have no control over when an accident happens, if it happens, and to what degree it happens,” he said. “If an incident is pretty serious or happens to affect multiple individuals, those limits can get used up pretty quickly. It is good to have an extra layer.”
We have no control over when an accident happens, if it happens, and to what degree it happens. … It is good to have an extra layer [of liability coverage].
Owners should also distinguish liability protection from coverage for damage to their own building, Anaya said. Commercial Property Insurance can respond to damage from perils such as wind and fire, but wear and tear would generally not be covered, she said.
“[CGL Insurance and Commercial Property Insurance] go hand in hand. They are both very important,” she said. “If the building burns down, there goes your whole asset.”
[CGL Insurance and Commercial Property Insurance] go hand in hand. They are both very important.
For property owners, “it can help you sleep at night knowing you have the right coverages,” Anaya said.
Building owners should understand how their policy may respond to risks such as vandalism and graffiti, which may be more common at vacant properties, as well as whether required code upgrades would be covered following damage claims. Policy enhancements are available to address vandalism, while Ordinance and Law Coverage can help with the additional costs associated with bringing a building up to code during repairs, Villalvazo pointed out.
“A lot of times, [Ordinance and Law] is a coverage that gets overlooked, especially on an older building,” he said.
Prioritizing maintenance as costs rise
Rising repair costs can make building upkeep more challenging, but postponing maintenance can allow hazards to develop, Anaya explained. “Everything has gone up,” she said. “The cost of materials is more expensive, and that can make it more difficult for building owners to maintain their buildings.”
Owners should check their vacant properties at least bi-weekly for damage, unauthorized occupants, and other concerns, Anaya recommended. Owners who need help evaluating a building’s condition can hire contractors to assess repair needs and electrical systems.
“You have to keep up with your buildings — your assets — because accidents can happen,” she said. “It is about taking care of your building and just looking for damages, looking for any leaks or a crack on the floor, and just being aware.”
These checks can help owners identify problems before they result in an injury or property damage claim, Villalvazo said.
“A claim is something everybody is always trying to avoid,” he said. “One of the best ways to do that is to do your own check around your property and look for anything that could be a problem. Addressing anything like that upfront will always be a better course of action rather than waiting for a claim to happen. That can save you the headache of a claim long-term.”
When purchasing CGL Insurance, Excess Liability Insurance, or Commercial Property Insurance, asking questions about coverage differences is key, he added.
“At the end of the day, our job as underwriters is to find the best coverage available for that risk,” Villalvazo said. “Take the time to review what you are buying, especially because a lot of times these purchases are thousands of dollars. Use the resources available to you and ask those questions so you have confidence in what you are buying.”