Intel

Featured
Med Spa Hit With $25,000 Penalty Over Unauthorized Drugs
Inside This Article: An Ohio med spa was fined $25,000 after investigators found unauthorized prescription drug orders and other violations. A patient lost consciousness after using a drug provided by one of the med spa’s owners, according to the state investigation. Medical Malpractice Insurance and Commercial General Liability (CGL) Insurance can address different aspects of med spa risks. As
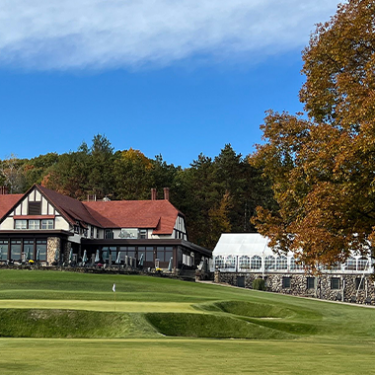
Century-Old Clubhouse Destroyed by Fire Faces Complex Rebuild
Inside This Article: A fire recently destroyed the historic Lochmoor Country Club clubhouse in Grosse Pointe Woods, Michigan. Historic properties may require specialized Commercial Property Insurance with Historical Replacement Cost to reproduce original materials, designs, and craftsmanship after a loss. Business Interruption Coverage and Extra Expense Coverage can help companies recoup lost revenue and maintain payroll during restoration. Updates
In the News

Trending
Other Recent Intel
Seemingly minor changes in policy language can create significant coverage gaps for Construction risks. In this webinar, Burns & Wilcox experts discuss key terms, conditions, and exclusions that can influence underwriting decisions and claim outcomes, including action-over, subcontractor exclusions, hot work operations, subsidence exposures, residential limitations, and work height restrictions. Featured experts: David Gross, Vice President, Managing Director, Broker, Casualty, Burns &…
Why It Matters: Construction risk extends well beyond jobsite injuries and physical damage. Design decisions, subcontractor errors, and project management oversights can create liability exposures that may not become apparent until months or years after a project is completed. While construction firms typically carry Commercial General Liability (CGL) Insurance to cover third-party property damage and bodily injuries, many losses in this industry stem from…
Why It Matters: Serious liability claims can arise from everyday situations involving properties, vehicles, recreational activities, pets, and other personal exposures. Rising costs and social inflation are contributing to larger and more severe outcomes. Individuals with significant assets, youthful drivers in the household, watercraft, swimming pools, trampolines, short-term rental properties, or higher public visibility may face increased liability risks. Reviewing liability limits…
Scenario 1: An older apartment complex experienced a catastrophic boiler failure, resulting in carbon monoxide exposure and multiple illnesses among residents. The prior insurance policy included both a total pollution exclusion and a punitive damages exclusion—leaving the property owner exposed to significant uncovered losses. RELATED STATS: After the incident, the broker worked to restore broader coverage for the client, including…
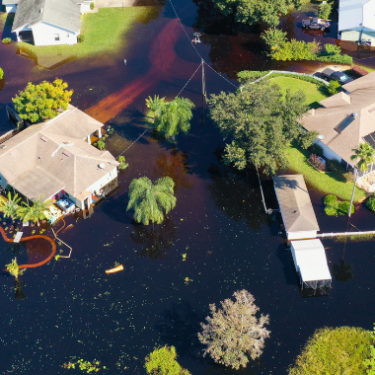
Flood events have surged over the past decade, putting many Residential and Commercial properties, including those outside of traditional flood zones, at risk. Parametric Flood Insurance provides data-driven, trigger-based financial protection for certain exposures, while Traditional Flood Insurance remains a foundational coverage for many property owners. Each product serves a distinct role and can be used independently or together to support a more…
Why It Matters: Medical spas continue to expand the range of services they offer, from aesthetic procedures to weight loss, IV therapies, and alternative, regenerative, or off-label treatments. As offerings evolve, coverage may be impacted by how services are delivered, who performs them, and whether treatments—including non-FDA-approved or compounded products—are disclosed and contemplated within the policy. Policies may include exclusions, limitations, or require specialized coverage to address…
Powered by